Equipment can be one of the largest investments a business makes.
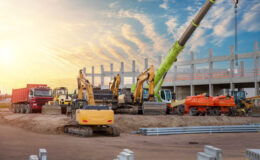
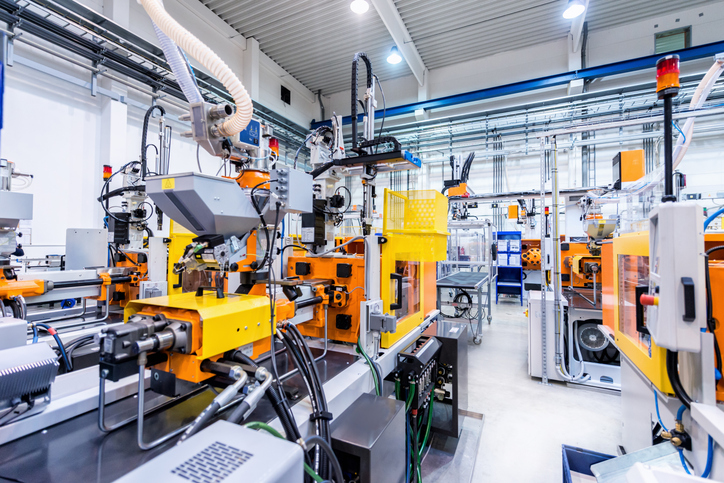
A construction company may need an excavator. A transportation company may need trucks. A manufacturer may need new machinery. A medical practice may need specialized equipment.
The problem is that paying cash for equipment can consume working capital that the business needs for payroll, inventory, materials, marketing, expansion, and everyday operating expenses.
Equipment financing provides an alternative way to acquire the assets a business needs while spreading the cost over time.
LMC Alternative Business Capital offers equipment financing solutions designed to help businesses acquire essential equipment while managing available working capital. LMC currently advertises equipment financing programs ranging from $25,000 to $3 million, with program terms and qualification requirements varying by transaction.
What Is Equipment Financing?
Equipment financing allows a business to acquire eligible equipment and repay the financing over an agreed-upon term.
Depending on the structure, the equipment itself may serve as collateral.
Equipment financing can potentially be used for:
- Heavy construction equipment
- Manufacturing machinery
- Commercial vehicles
- Trucks
- Medical equipment
- Restaurant equipment
- Industrial machinery
- Agricultural equipment
- Technology and specialized equipment
- Other qualifying business assets
The type of equipment that can be financed depends on the lender and financing program.
Why Finance Equipment Instead of Paying Cash?
Consider a business purchasing $250,000 of equipment.
Paying cash eliminates a monthly payment—but it also removes $250,000 from the company’s available liquidity.
That money could otherwise be used for:
- Payroll
- Inventory
- Materials
- Marketing
- Expansion
- Emergency reserves
- New contracts
- Working capital
Equipment financing can allow the company to acquire the equipment while preserving some of its available cash.
For a growing company, that liquidity can be extremely valuable.
Equipment Financing for Growing Businesses
Equipment financing can be particularly useful when a business has an opportunity to grow but needs additional assets to do it.
Imagine a contractor receives a large new contract.
The company now needs another excavator, dump truck, or specialized piece of machinery to complete the work.
The equipment may generate additional revenue—but purchasing it outright could create a significant cash-flow strain.
Financing the equipment can potentially allow the company to acquire the asset while retaining capital for the project itself.
This is one reason equipment financing should be viewed as more than simply a way to buy machinery.
It can also be a working capital management strategy.
What Equipment Can Be Financed?
Equipment financing can potentially apply to a wide range of business assets.
Construction Equipment
- Excavators
- Skid steers
- Loaders
- Cranes
- Bulldozers
- Dump trucks
- Concrete equipment
- Paving equipment
Transportation Equipment
- Commercial trucks
- Trailers
- Work vans
- Fleet vehicles
Manufacturing Equipment
- CNC machinery
- Production equipment
- Packaging equipment
- Industrial machinery
Medical Equipment
- Diagnostic equipment
- Dental equipment
- Medical devices
- Treatment equipment
Restaurant Equipment
- Commercial ovens
- Refrigeration
- Cooking equipment
- Food preparation equipment
LMC specifically highlights construction, manufacturing, medical, vehicle, and commercial equipment among the types of assets its equipment financing can support.
Can You Finance Used Equipment?
Depending on the financing program, eligible used equipment may be financeable.
Used equipment can make sense for businesses that want to control acquisition costs while still obtaining productive assets.
However, lenders may evaluate factors such as:
- Equipment age
- Condition
- Value
- Manufacturer
- Useful life
- Purchase price
- Intended use
The financing structure can vary considerably depending on the asset.
How Do You Qualify for Equipment Financing?
Equipment financing requirements vary by lender and program.
Potential considerations include:
- Credit profile
- Time in business
- Revenue
- Cash flow
- Existing debt
- Equipment type
- Equipment value
- Down payment
- Business experience
LMC’s current equipment financing page lists multiple qualification pathways and notes that requirements vary by financing program, including different credit and business-history considerations.
That is important because business owners shouldn’t assume that one lender’s requirements represent the entire equipment financing market.
Equipment Financing for Startups
New businesses may face more challenges obtaining traditional financing because they have limited operating history.
However, equipment financing can sometimes provide an alternative because the equipment itself may provide collateral value.
Startups should be prepared to provide information about:
- Business ownership
- Industry experience
- Business plan
- Equipment purchase
- Vendor quote
- Expected revenue
- Available capital
- Personal credit
- Projected cash flow
Approval depends on the specific financing program and overall transaction.
Equipment Financing vs. Equipment Leasing
Equipment financing and leasing can both provide access to equipment without requiring the business to pay the entire acquisition cost upfront.
The major difference is the ownership structure.
With equipment financing, the business generally acquires the equipment and makes payments toward ownership.
With leasing, the business generally pays for the use of the equipment under the terms of the lease.
The better option depends on:
- How long you plan to use the equipment
- Whether ownership matters
- Expected equipment life
- Cash flow
- Replacement cycle
- Tax considerations
- Financing costs
Businesses should compare the total economics rather than simply looking at the monthly payment.
How Much Equipment Financing Can You Get?
The amount depends on the equipment, borrower, financing program, lender, and transaction.
LMC currently advertises equipment financing programs from $25,000 to $3 million, although actual approval amounts and terms are subject to underwriting and program requirements.
For larger equipment purchases, borrowers should consider the entire capital structure.
For example, financing the equipment may preserve working capital that can then be used to support the revenue-producing activity associated with the asset.
The Best Equipment Financing Isn’t Always the Lowest Payment
Business owners often focus on monthly payment.
But a better analysis includes:
- Total financing cost
- Term
- Interest rate
- Down payment
- Early payoff provisions
- Ownership
- Equipment useful life
- Expected revenue
- Maintenance
- Insurance
- Depreciation
- Cash-flow impact
A low monthly payment can sometimes mean a longer term and greater total financing cost.
The goal should be to structure financing that makes sense for the business—not simply to minimize the monthly payment.
Equipment Financing for Construction Companies
Construction companies are particularly dependent on equipment.
A contractor may need to purchase equipment before receiving payment on a major project.
That creates a working capital challenge.
Equipment financing can potentially allow the contractor to acquire the machinery needed to complete the contract while preserving cash for:
- Payroll
- Materials
- Fuel
- Subcontractors
- Insurance
- Project expenses
LMC has already developed construction-specific equipment financing content because of the significant role equipment plays in contractor growth.
How LMC Alternative Business Capital Can Help
Equipment financing should be evaluated as part of the company’s overall financial strategy.
LMC Alternative Business Capital helps businesses explore equipment financing and other commercial financing solutions based on their needs, financial position, and growth objectives.
Need to Finance Equipment?
Whether you’re purchasing a $50,000 piece of equipment or a multimillion-dollar asset, the financing structure matters.
Contact LMC Alternative Business Capital to discuss your equipment purchase and explore potential financing options.
Frequently Asked Questions
What is equipment financing?
Equipment financing allows a business to acquire eligible equipment and repay the cost over an agreed-upon financing term.
Can equipment financing preserve working capital?
Yes. Financing an equipment purchase can allow a business to retain more cash for operating expenses and growth rather than paying the entire purchase price upfront.
Can you finance used equipment?
Depending on the lender and program, eligible used equipment may qualify for financing.
How much equipment financing can I get?
LMC currently advertises equipment financing programs ranging from $25,000 to $3 million, although actual amounts depend on underwriting and the specific transaction.
Can startups get equipment financing?
Some equipment financing programs may consider newer businesses, although requirements can be more stringent and may depend on the owner’s experience, credit profile, equipment, and overall transaction.
What credit score is needed for equipment financing?
Requirements vary by lender and program. There is no single credit score requirement across the entire equipment financing market.
Should I finance or lease equipment?
The answer depends on whether your business wants ownership, how long it plans to use the equipment, cash flow, replacement cycles, and the economics of the financing agreement.