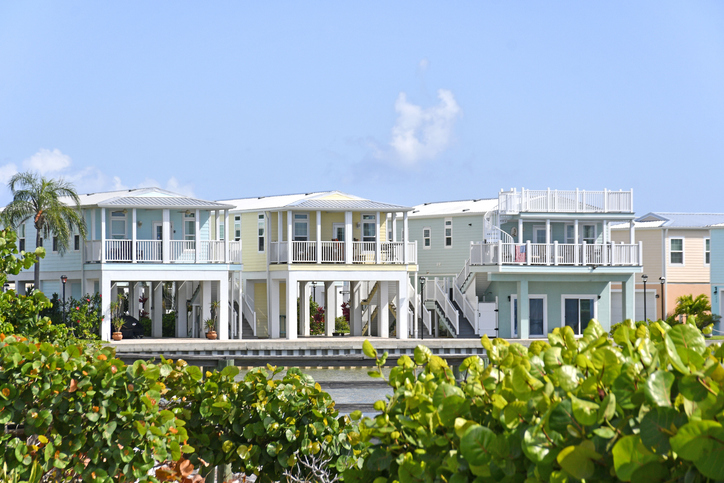
Whether you’re investing in Miami, Tampa, Orlando, Jacksonville, Fort Lauderdale, Fort Myers, Naples, Sarasota, or another Florida market, LMC can help evaluate the property, rental income, financing structure, and available DSCR loan options.
DSCR Loans in Florida for Real Estate Investors
LMC Alternative Business Capital provides DSCR loans throughout Florida for real estate investors purchasing, refinancing, and expanding rental property portfolios. Florida DSCR financing can allow qualified investors to qualify based primarily on the cash flow of the investment property rather than traditional personal-income documentation.
Supercharge Your Investment Potential with DSCR Loans!
Debt Service Coverage Ratio (DSCR) loans are designed specifically for real estate investors who want to scale their portfolios without the limitations of traditional income verification.
Instead of relying on tax returns, W-2s, or pay stubs, DSCR loans evaluate whether your property’s rental income can cover its debt obligations—making them one of the most powerful financing tools for investors today
Why Leverage DSCR Loans?
- Bypass Tax Returns: Secure funding based solely on your property’s cash flow.
- Slash High Rates: Eliminate the exorbitant rates and points associated with private loans.
- Fast-Track Approvals: Sidestep lengthy processes and rigid lending criteria.
Let your property’s income drive your next investment opportunity. Invest smarter and scale your portfolio faster.
Master the ins and outs of DSCR loans, understand the mechanics, and nail the qualifications. Seize this game-changing opportunity today!
DSCR Loan Program
A popular non-bank alternative for borrowers with 1-4-unit investment scenarios.
Maximize your investment strategy with a Debt Service Coverage Ratio (DSCR) loan.
Break free from the constraints of traditional debt-to-income ratios. Eliminate the headache of tax return documentation. Build your portfolio without relying on personal income. Surpass agency limits on property ownership.
Unlock your real estate potential with flexible lending built for professional investors.
Program Overview
- Loan size: $100,000 to $2,000,000
- Purpose: Purchase, Refinance, Cash Outs, Rehab
- Loan term: 30-Year Fixed
- Amortization: up to 30 years
- LTV: up to 80%
- FICO: Credit friendly and no minimum credit score program available
- DSCR: 0.75x
- Documentation: Light docs, No tax returns, proof of income or DTI required
- Foreign nationals welcome
Eligible Property Types
- 1-4-unit attached/detached
- Short-term rentals (Airbnb)
- Warrantable and non-warrantable condos
DSCR FAQs
What is a debt service coverage ratio (DSCR)?
The debt service coverage ratio (DSCR) measures an entity’s ability to service its debt obligations from operating income. It is calculated as:
DSCR = Net Operating Income ÷ Debt Service
Where:
- Net Operating Income (NOI) = Gross Operating Revenue − Operating Expenses
- Debt Service = Principal Repayment + Interest Payments + Lease Payments
A DSCR above 1.0 indicates sufficient cash flow to meet debt obligations, while a ratio below 1.0 signals potential default risk.
How do I calculate net operating income?
Net Operating Income represents the property’s revenue-generating capacity after accounting for direct operational costs. The formula is:
NOI = Gross Operating Income − Operating Expenses
Gross Operating Income encompasses all rental revenue streams, including base rent, parking fees, and ancillary income. Operating Expenses comprise property management fees, maintenance and repairs, property taxes, insurance premiums, utilities (when landlord-paid), and HOA assessments.
Note that NOI excludes debt service (mortgage payments), non-cash expenses such as depreciation and amortization, and capital expenditures (CapEx). This distinction is critical for accurate valuation metrics, particularly when calculating capitalization rates or performing discounted cash flow analysis.
What is considered a good debt service coverage ratio?
Industry standards typically require a minimum DSCR of 1.25x, which demonstrates sufficient cash flow cushion to service debt obligations. However, certain lenders—including Figure—may underwrite loans with DSCRs as low as 1.0x when compensating factors such as borrower creditworthiness and asset class characteristics support the risk assessment.
What are the advantages of a DSCR loan?
DSCR loans offer several distinct advantages for real estate investors and financial advisors:
Alternative Underwriting Criteria: DSCR loans qualify borrowers based on the property’s debt service coverage ratio rather than personal income documentation. This allows investors with substantial assets but limited W-2 income to access financing that would otherwise be unavailable through conventional channels.
Portfolio Scalability: Unlike conventional mortgages, which typically impose a 10-property limit, DSCR loans generally have no cap on the number of financed properties. This enables investors to scale their portfolios more aggressively without hitting artificial lending constraints.
Expedited Processing: DSCR loans often feature shorter closing timelines due to streamlined documentation requirements, eliminating the need for tax returns, pay stubs, and extensive income verification.
Simplified Documentation: The absence of employment and income verification requirements reduces administrative burden and accelerates the approval process, particularly beneficial for self-employed investors or those with complex income structures.
Call Us To Secure Your Financing
Use the contact form below to chat with an expert today.
"*" indicates required fields